Most financial advice for expats is built around the adviser's interests, not yours.
Understanding how financial advice works — and where conflicts of interest arise — is the first step to making better decisions about your money. This site provides clear, impartial information on financial planning for internationally mobile professionals.
Why this matters Speak to AndrewUnderstanding the landscape
What every expat should know about financial advice
Before engaging any financial adviser, it helps to understand the structures, incentives, and conflicts that shape the advice you receive.
Conflicts of Interest
When an adviser's pay is tied to the products they sell, there is a structural incentive to recommend what pays the most rather than what suits the client best. Lock-in periods and high exit fees are common indicators of commission-driven recommendations.
Fee-Based vs. Commission-Based Advice
Fee-based advisers are paid directly by the client. Commission-based advisers are paid by product providers. "Free" advice is funded through product commissions — the cost is embedded in the product rather than disclosed transparently.
Regulatory Oversight
Advisers regulated in the UK, Australia, or Singapore operate under established conduct rules and consumer protection frameworks. Much of the offshore financial services industry operates in jurisdictions with materially weaker oversight.
Holistic Financial Planning
Good planning begins with a thorough understanding of a client's circumstances, tax position, and goals across all relevant jurisdictions. Product recommendations, where appropriate, follow from the plan — they do not drive it.
Cross-Border Tax Complexity
Expats often have tax obligations in more than one country simultaneously — through residency, domicile, pension income, or investments. Tax-aware financial planning is essential, not optional, for internationally mobile individuals.
Pension Planning Across Borders
UK and Australian pension schemes have distinct rules that become significantly more complex when an individual has lived in multiple countries. Understanding what you have, what it's worth, and how it interacts with your overall position requires specialist knowledge.
Investment principles
What actually drives investment outcomes
Three factors determine the majority of long-term investment returns: how assets are allocated, how much is paid in costs, and whether a clear philosophy is consistently maintained.
Asset allocation drives returns
Research by Brinson, Hood and Beebower found that the split between equities, bonds, and cash accounts for approximately 90% of portfolio return variation over time. Which securities are held, or when positions are traded, explains remarkably little. Getting the allocation right matters more than almost any other decision.
Costs are the most controllable variable
Every percentage point in annual fees permanently removes that return from your portfolio. Unlike markets, costs are entirely within your control. Over a 20–30 year horizon, the compounding effect of high charges — from actively managed funds, adviser commissions, or platform fees — can substantially reduce the final outcome. Low-cost index funds outperform most active alternatives primarily because of this.
A documented investment philosophy
A clear, written philosophy prevents emotionally driven decisions during volatility, ensures consistency, and provides a basis for evaluating whether any proposed investment is appropriate. An adviser without one is more likely to be guided by short-term noise than long-term evidence.
Diversification and time horizon
Spreading investments across asset classes and geographies reduces the impact of any single loss. Combined with a time horizon appropriate to your goals, it is one of the most effective risk management tools available — and free to implement through low-cost index funds.
Behavioural discipline
The gap between what a fund returns and what the average investor in it actually receives is largely explained by poor timing: buying high, selling low. Keeping clients invested through volatility and preventing reactive decisions is often a financial planner's most valuable function.
Understanding volatility
Volatility is not the risk. Reacting poorly to it is.
Volatility is not a flaw in the investment system — it is a feature of it. Short-term price swings are driven by sentiment. Over the long term, markets have consistently advanced. The two are not in contradiction. Volatility is simply the price investors pay for long-term outperformance.
Financial media is structurally focused on the next few days or weeks. For investors with a properly constructed long-term plan, market noise is largely irrelevant. Over the last 75 years, the average intra-year market decline has been around 14%. Markets have advanced in approximately three out of every four calendar years. Every significant decline has been followed by a full recovery.
Where short-term volatility causes real damage is in specific situations: over-leveraged investors, illiquid products, or funds with high embedded fees. In those cases, falling markets amplify the cost of prior poor decisions. This is why portfolio construction matters before volatility arrives, not during it.
A strategy built to withstand volatility
A detailed financial plan aligned to long-term goals — not the current market narrative.
Sufficient cash and short-term bonds to cover near-term needs without touching long-term investments.
Long-term assets in broadly diversified, low-cost index funds — giving access to global markets at minimal cost.
What actually damages wealth
Market declines are temporary. Poor financial guidance is not.
Markets have always recovered from downturns. The same cannot be said of damage caused by structurally poor advice. These are the actual wealth destroyers — most of which are entirely avoidable.
High costs buried in complex products
Annual management charges, platform fees, adviser commissions, and fund costs can combine to 2–4% per year in the offshore market — permanently eroding returns the client never sees.
Unnecessary trading costs
Frequent portfolio changes generate transaction costs and, in some jurisdictions, tax events. In a commission-based model, activity can also generate additional adviser remuneration. The evidence shows less trading produces better outcomes.
Products too complex to explain clearly
If an adviser cannot clearly explain how a product works, what it costs in total, and when it might underperform — that is a material warning sign. Complexity typically serves the product provider, not the investor.
Commission-based recommendations
A recommendation made by an adviser compensated through product commission is not independent advice. The incentive to recommend the most suitable product is structurally compromised from the outset.
A better approach
Goal-based investing: planning around outcomes, not risk scores
Traditional planning assigns a risk number and picks a portfolio. Goal-based investing starts elsewhere — with what the money is actually for, and when it will be needed. Time horizon, not a questionnaire, should determine how a portfolio is structured.
Risk-based approach
- Starts with a questionnaire
- Assigns a single risk number
- One portfolio for all needs
- Hard to explain or adjust
- Anxiety during market falls
Goal-based approach
- Starts with your goals and timeline
- Maps money to its purpose
- Separates near- and long-term needs
- Transparent and easy to adapt
- Calm — near-term needs already covered
Cashflow modelling
Seeing the full picture — in numbers and over time
A cashflow model is a dynamic projection of how your income, expenses, savings, and investments evolve over your lifetime. It sits at the centre of any well-constructed financial plan.
Rather than a static snapshot, a cashflow model projects forward through time. It can model different economic scenarios — changes to inflation, interest rates, or investment returns — and show how shifts in personal circumstances affect the plan.
When can you afford to retire? What happens to your family's finances if you can't work? Can you help your children onto the property ladder without derailing your own retirement? These questions have concrete answers when you can see the numbers play out.
For expats, the model captures income, pensions, and assets spread across multiple countries and currencies — giving a single coherent picture of financial position and trajectory.
How a cashflow model works
Establish current position
Income, assets, liabilities, pensions, and expenses across all jurisdictions are mapped in full.
Define goals and timelines
Retirement date, income needs, major expenditures, and legacy objectives are agreed and entered.
Project forward
The model runs over your lifetime, showing whether goals are achievable under base, optimistic, and stress scenarios.
Test scenarios
What if inflation runs higher? What if you retire two years early? The model answers these before decisions are made.
Review and update annually
Revisited each year to track progress and adjust for changes in circumstances, tax rules, or markets.
Particularly valuable for expats managing income, pensions, and assets across multiple countries and currencies.
A reference point
What good financial advice looks like
Before engaging a financial adviser, it is reasonable to expect the following from a properly structured, independent planning relationship.
Transparent fee disclosure
All fees disclosed clearly in writing before engagement — what you pay, how it's calculated, and when it's due.
Written financial plan
Recommendations documented in a written plan setting out your circumstances, objectives, and the reasoning behind each recommendation.
Needs-based analysis
Advice follows a thorough fact-find covering income, assets, liabilities, tax position, and goals — not a product demonstration.
No undisclosed commissions
Any remuneration received from a product provider must be disclosed. "Free" advice funded by hidden commissions is not independent.
Regulatory authorisation
The adviser should be authorised and regulated in a recognised jurisdiction, verifiable through the relevant regulatory register.
Ongoing review
A financial plan is not a one-off document. It should be reviewed regularly and updated when circumstances change.
Andrew Talbot CFP®
20+ years navigating the financial complexity of life across borders
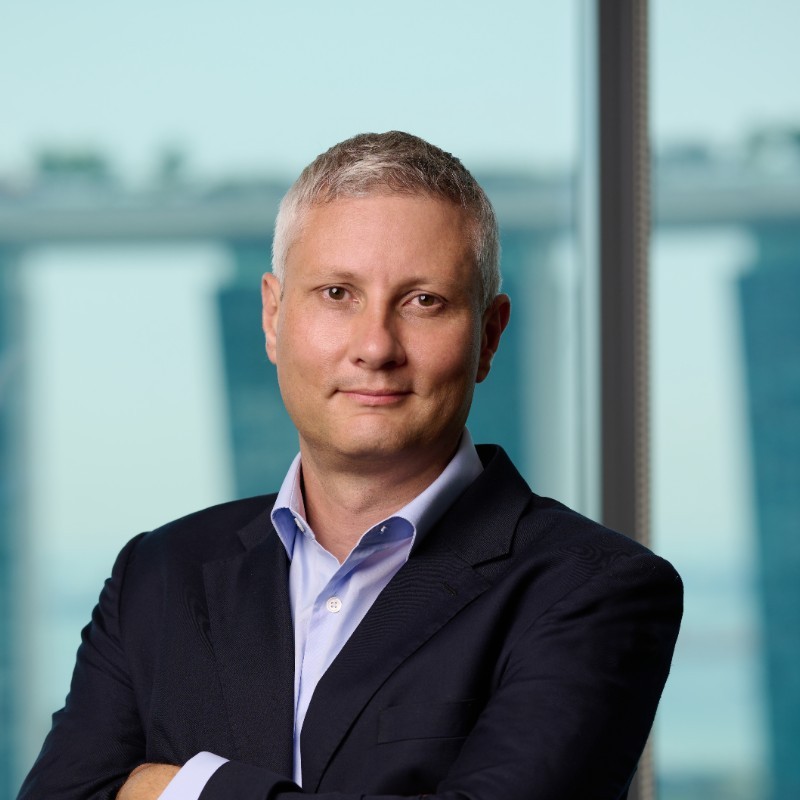
Managing significant wealth across borders is genuinely complex. Tax systems overlap. Pension rules change the moment you relocate. Structures that worked in one country can become liabilities in another.
I have spent 20+ years navigating exactly this — as both an expat myself and a Certified Financial Planner qualified in three jurisdictions: the UK, Australia, and Singapore.
My clients are international professionals and business owners with complex, multi-jurisdiction financial lives. They want a plan that travels with them — not one that has to be rebuilt from scratch every time they relocate.
What makes my practice different
- Fee-based only. No commissions. No product incentives. No hidden costs. You pay for a plan, not a sale.
- Three-jurisdiction qualified. CFP® credentials in the UK, Australia, and Singapore — covering cross-border solutions, offshore structures, and international tax planning.
- Long-term relationships. Many clients have been with me through multiple relocations.
Areas of focus
Cross-border wealth management · International tax planning · UK advice · Offshore investment portfolios · Retirement planning · Estate planning & international trusts · Education fee planning · Corporate benefit solutions
Enquiries
Get in touch
To enquire about financial planning services or arrange an initial consultation, get in touch by email or book a video call directly.
andrew@expatfinancialplanning.com
📅 Book a 30-minute consultation
Andrew Talbot CFP® on LinkedIn
Based in Singapore · Available to clients worldwide